New Homes in Willis, TX: What to Check Before Buying
Homeowner Info Mar 21, 2026 · 3 min read Updated: Sep 8, 2026
When comparing new homes in Willis, look at the particular neighborhood, home, and financing offer. A city name alone does not describe the commute, included features, or ownership costs you will have.
Test the commute from the homesite
Use the actual address and travel at the times you expect to drive. Check the route to work, shopping, appointments, and other regular destinations. Traffic and the distance to major roads can make a broad estimate less useful than an in-person trip.
Visit the neighborhood at more than one time of day when practical. Look at access, current construction, nearby lots, and the outdoor space around the home.
Verify schools and local services
If school assignments matter, contact the district using the specific property address. Do not assume a Willis postal address establishes a district, campus, or future boundary. Review the information that matters to you directly with the school rather than relying on a general rating claim.
For healthcare, childcare, or other services, confirm the provider and availability you need. A nearby building does not establish that a service will fit your requirements.
Compare the home and included package
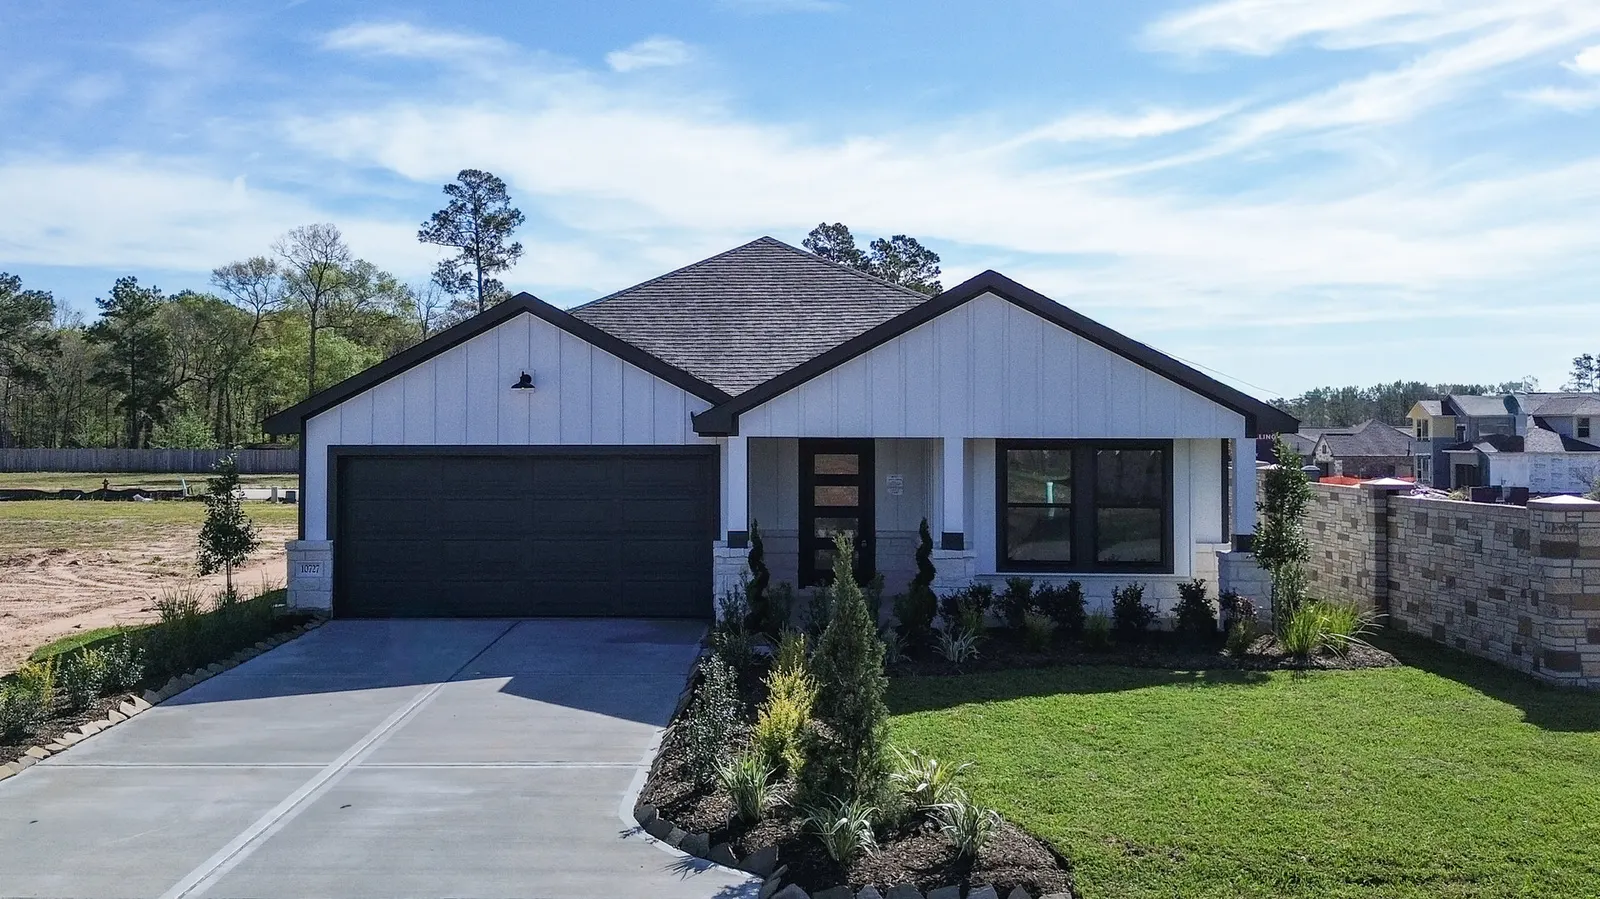
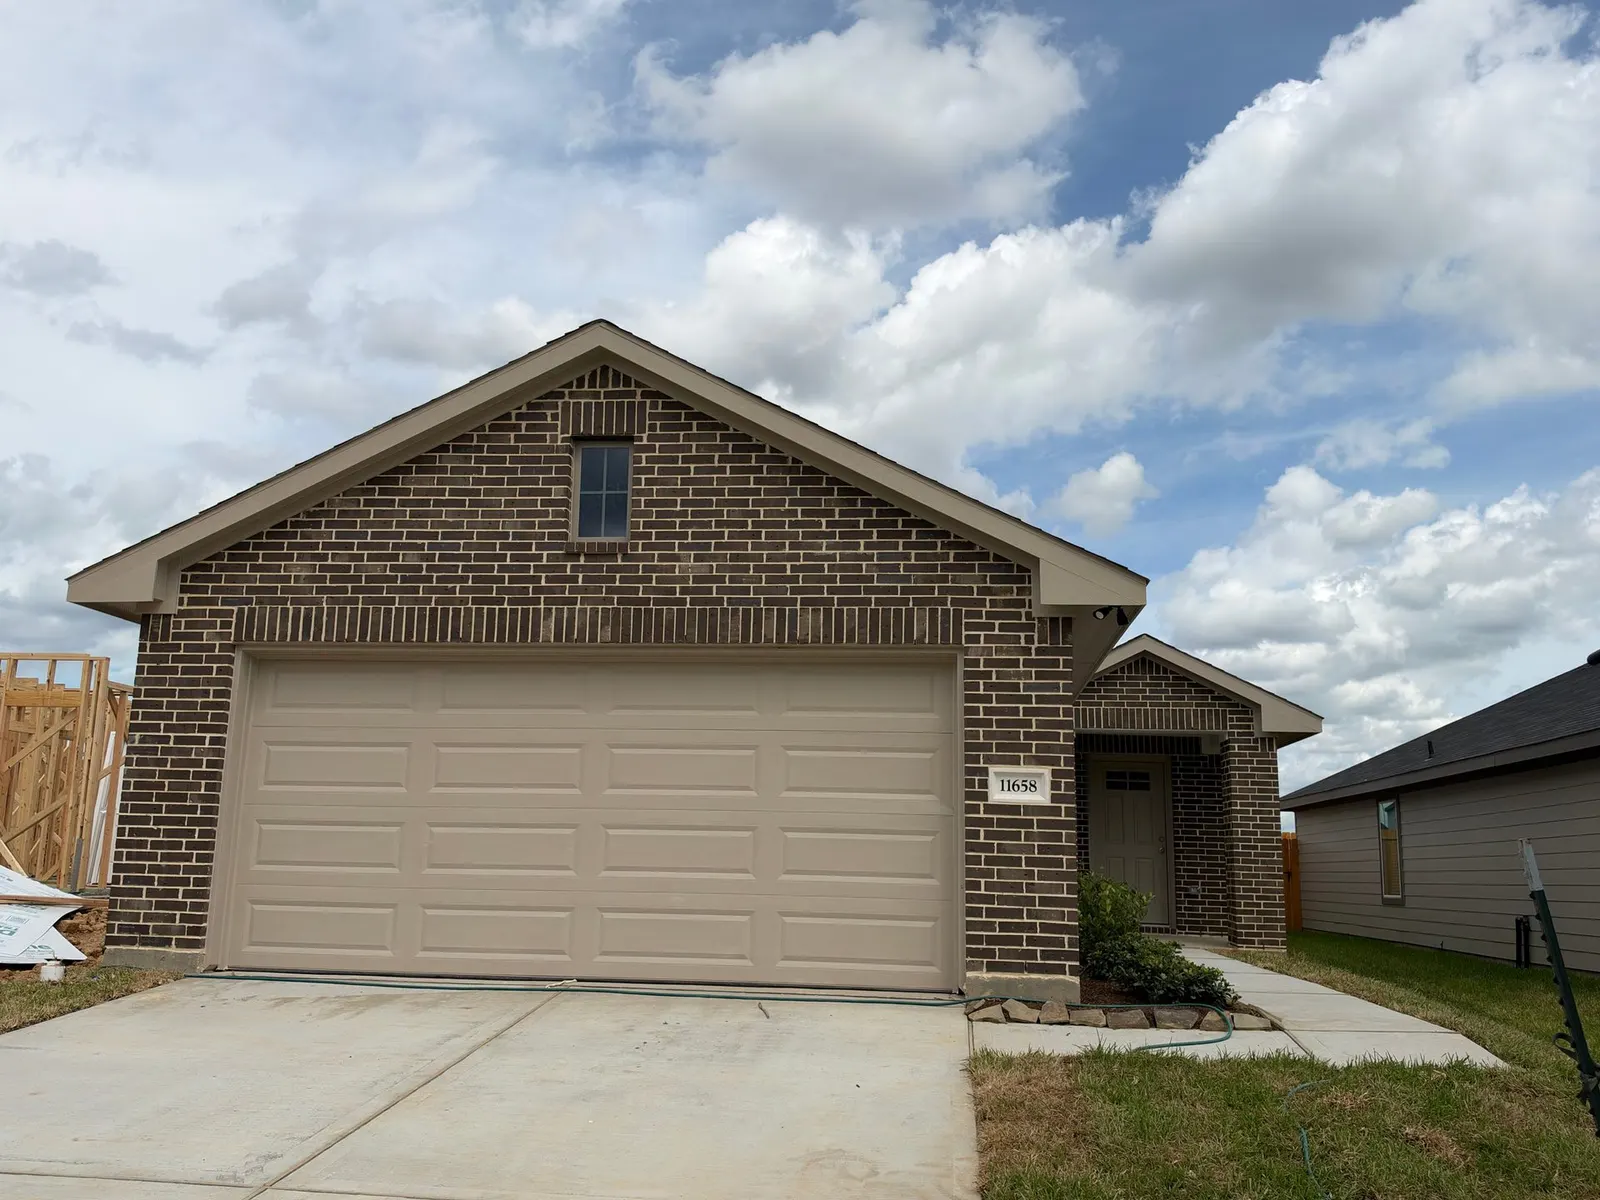
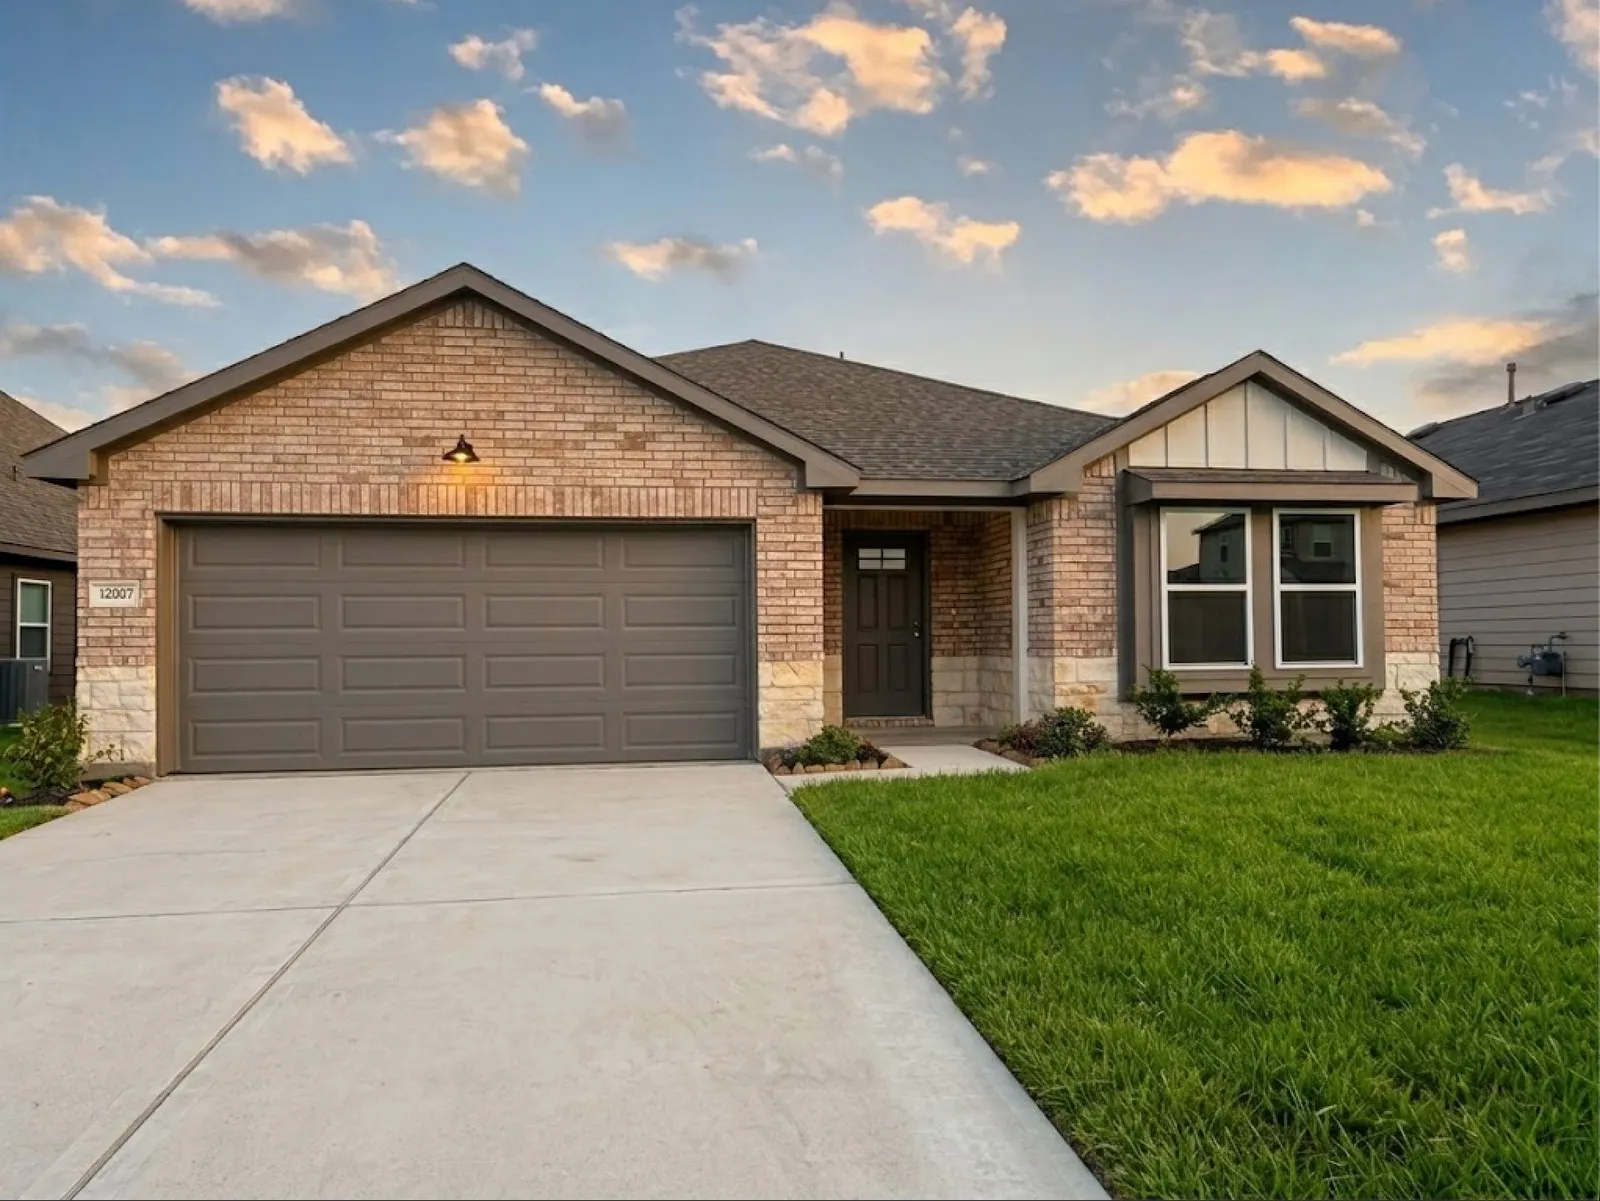
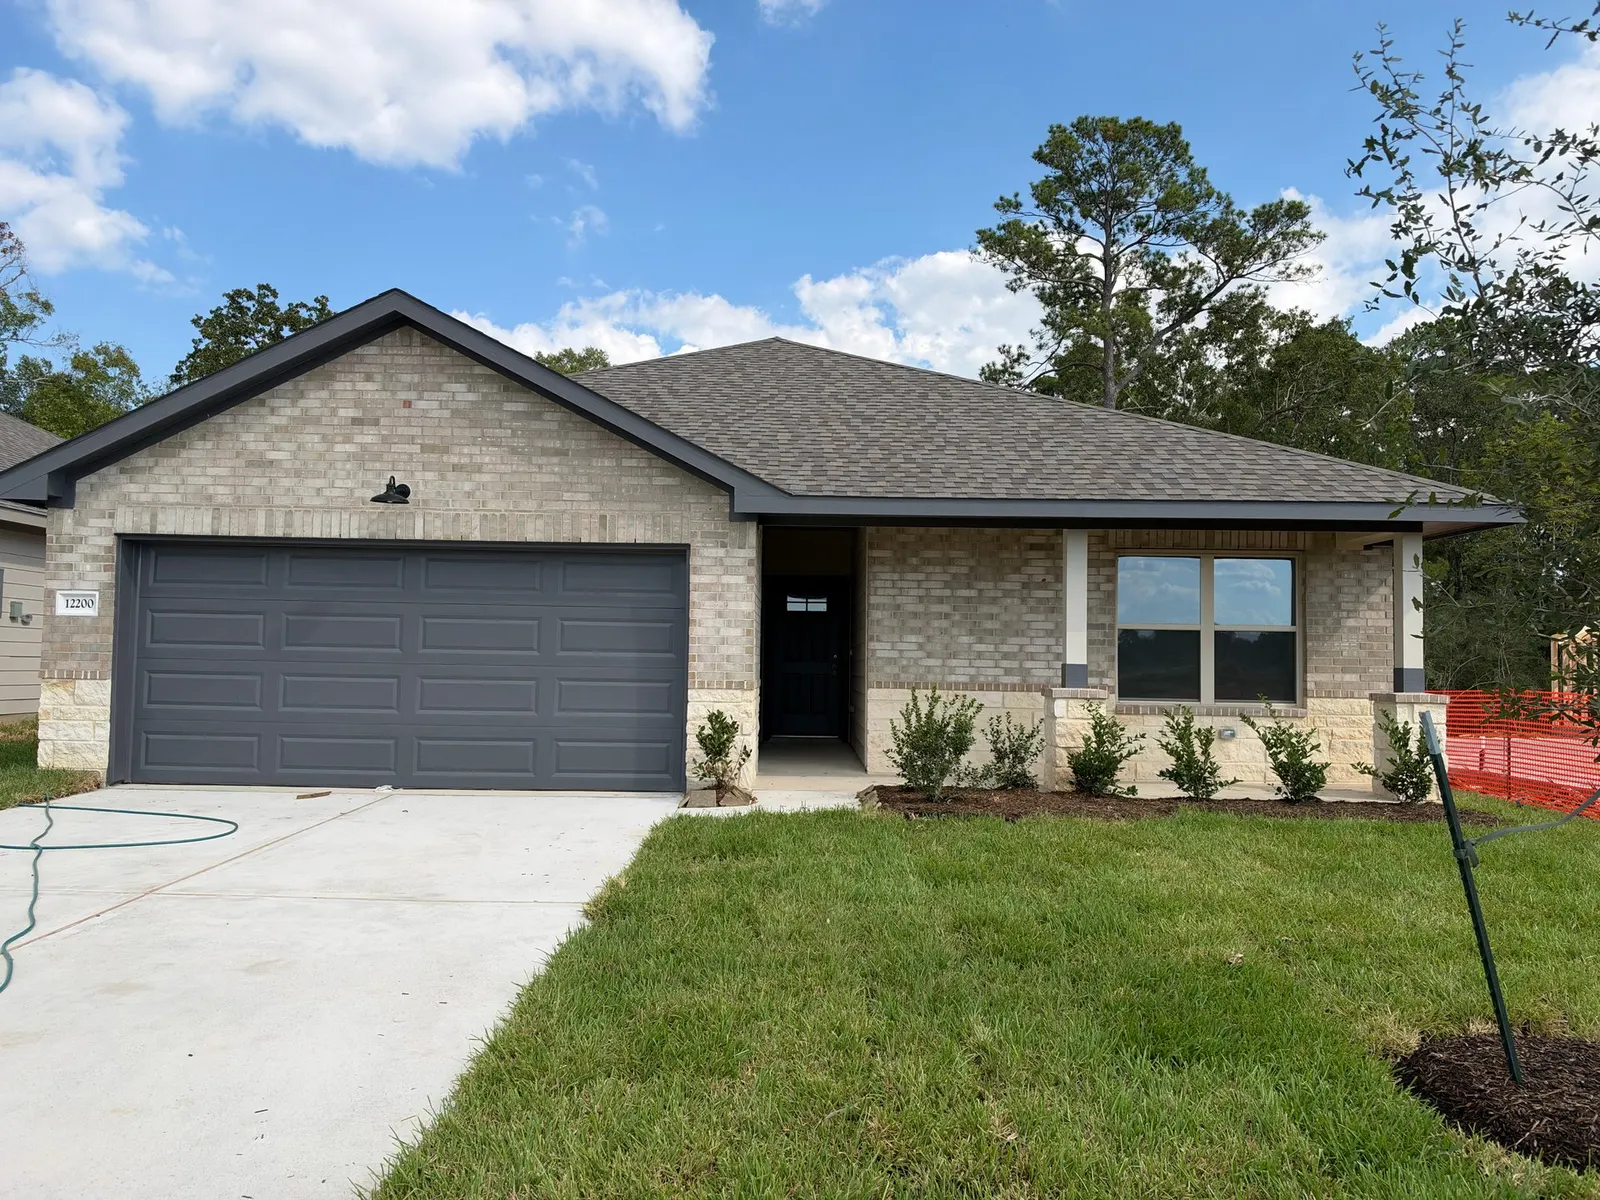
At Lexington Heights, the community page includes floor plans, available homes, community details, and a homesites map. Use the map to understand where a listing sits in the neighborhood, then verify the home’s version of the plan and elevation.
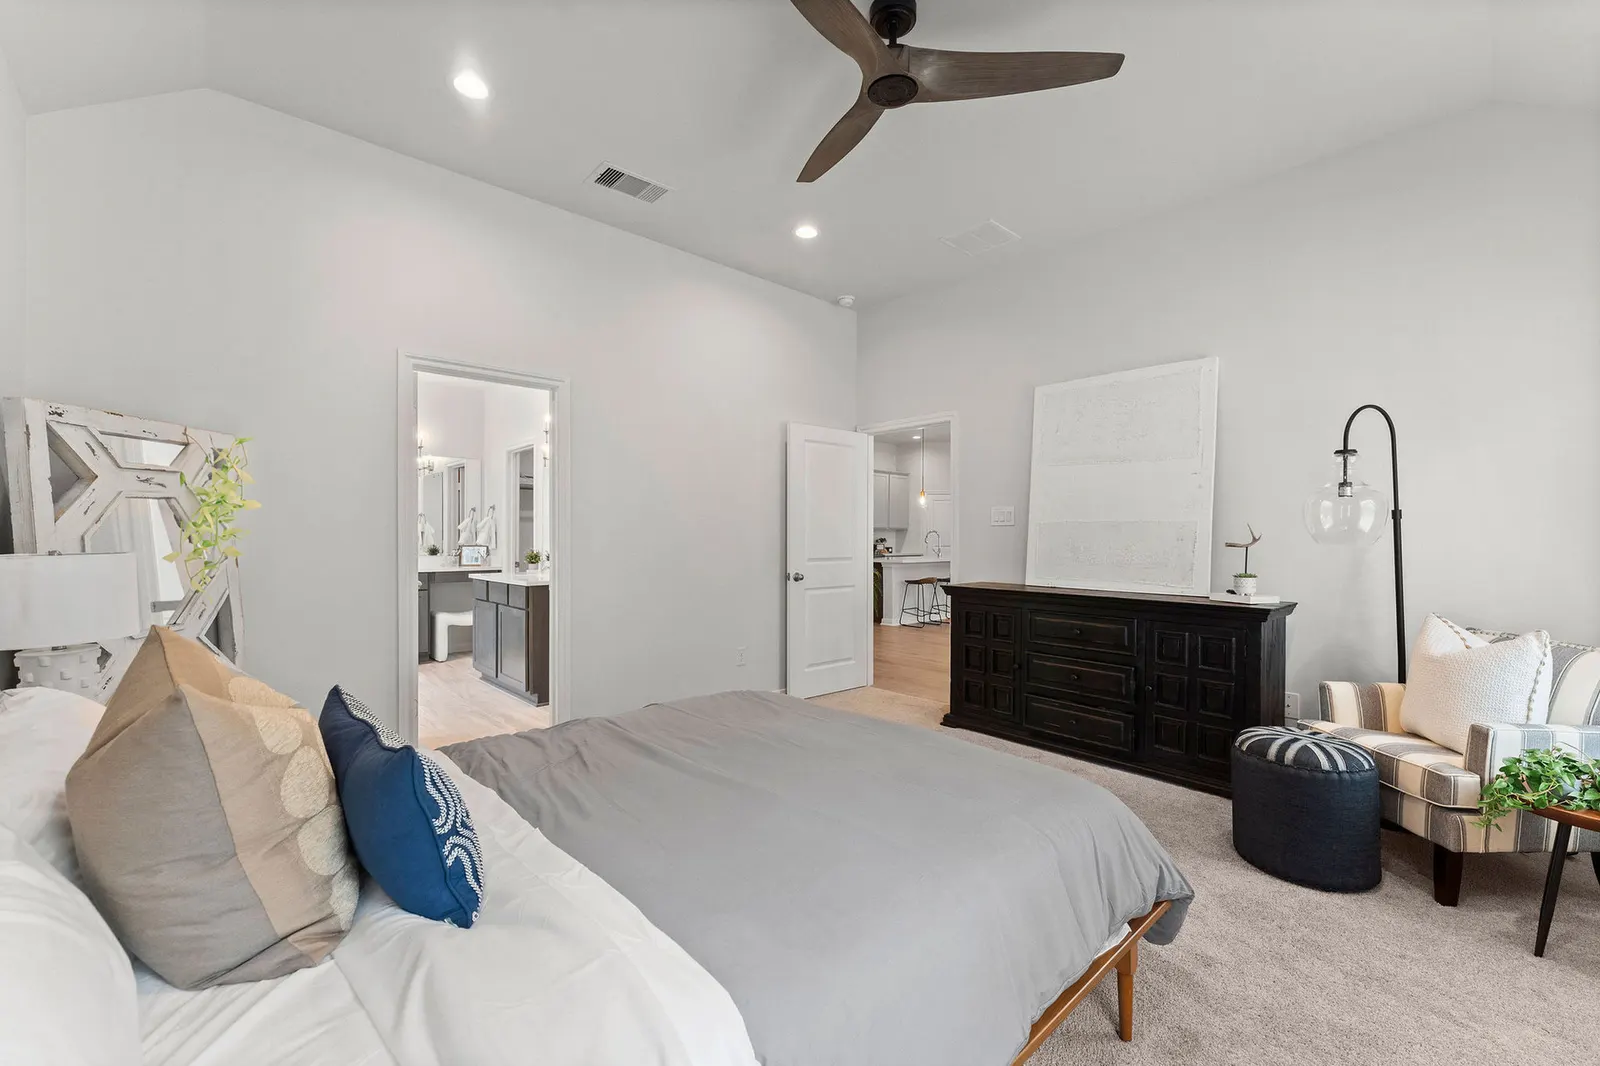
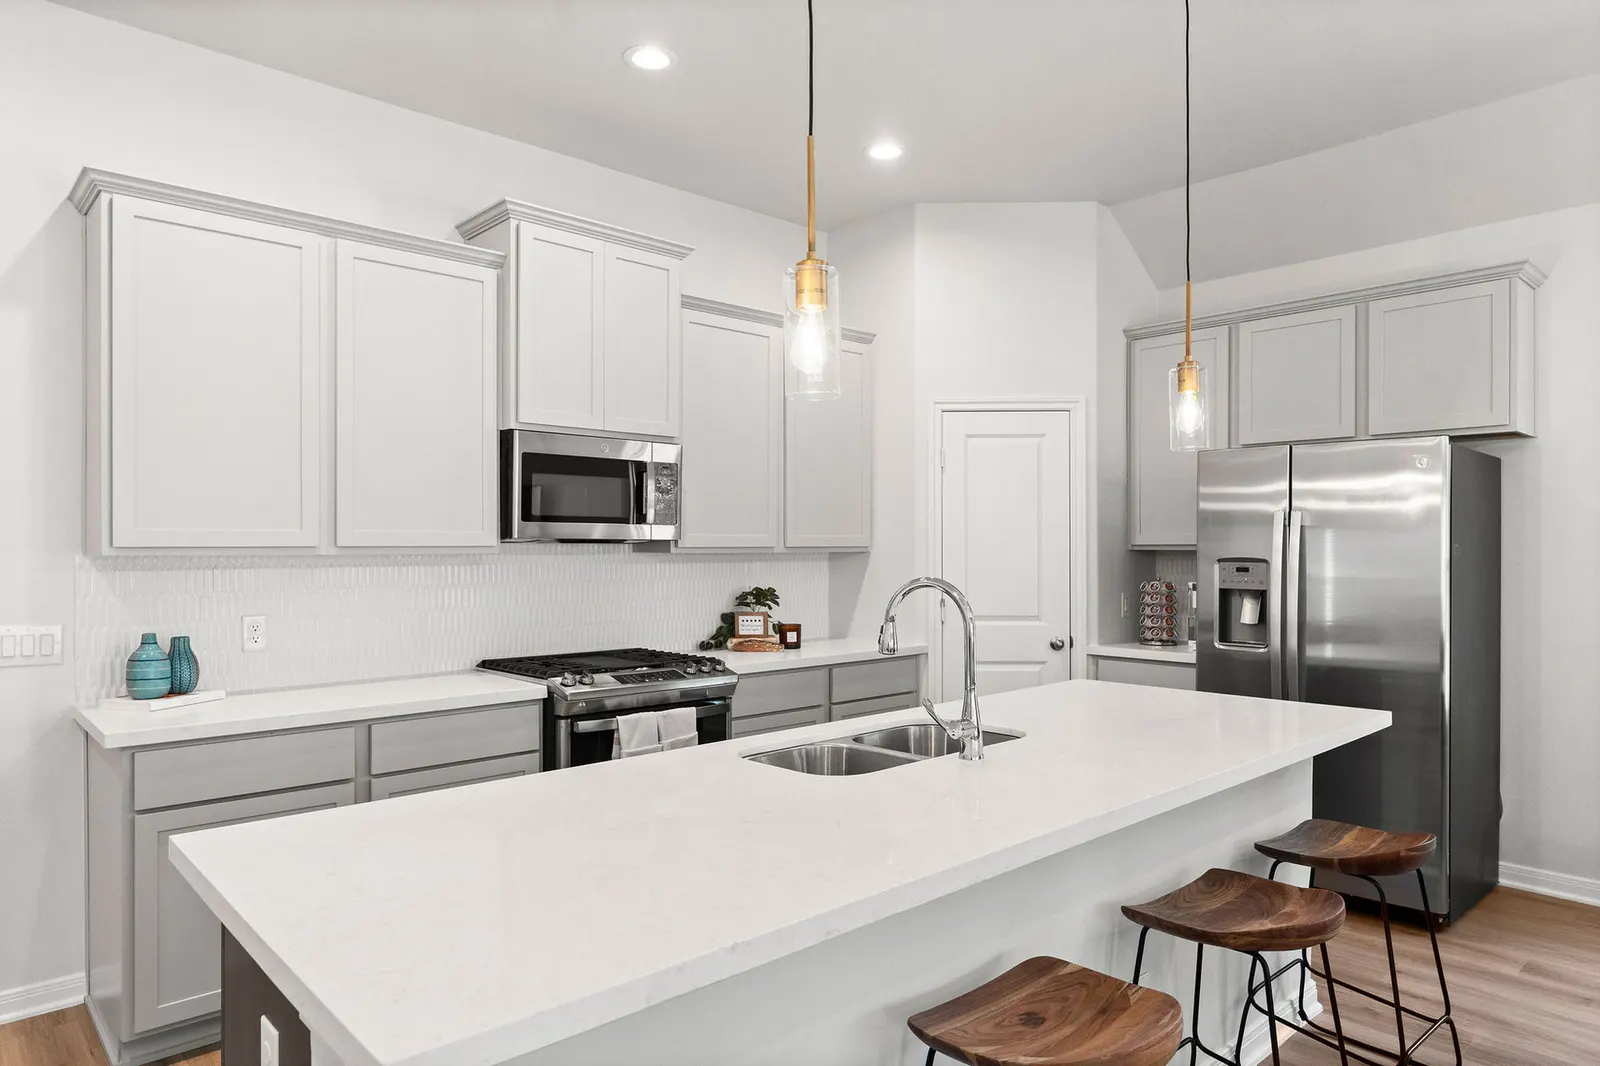
Review the included-features sheet for the community. Ask which choices remain, which finishes are selected, and whether an item shown in a model or photograph is optional.
Get current costs for the address
Start with the listing’s current price and ask a lender for the loan figures that apply to you. Request estimates of property taxes, insurance, association dues, and other ownership expenses. Keep maintenance and moving funds in the budget.
If an incentive is available, confirm the covered homes, deadline, qualifications, and required transaction partners. An archived blog post’s rate or starting price is not a current offer.
If you are exploring USDA financing, have the lender check both your household and the property. The no-down-payment guide explains the questions to ask without assuming all of Willis qualifies.
Confirm timing and documents
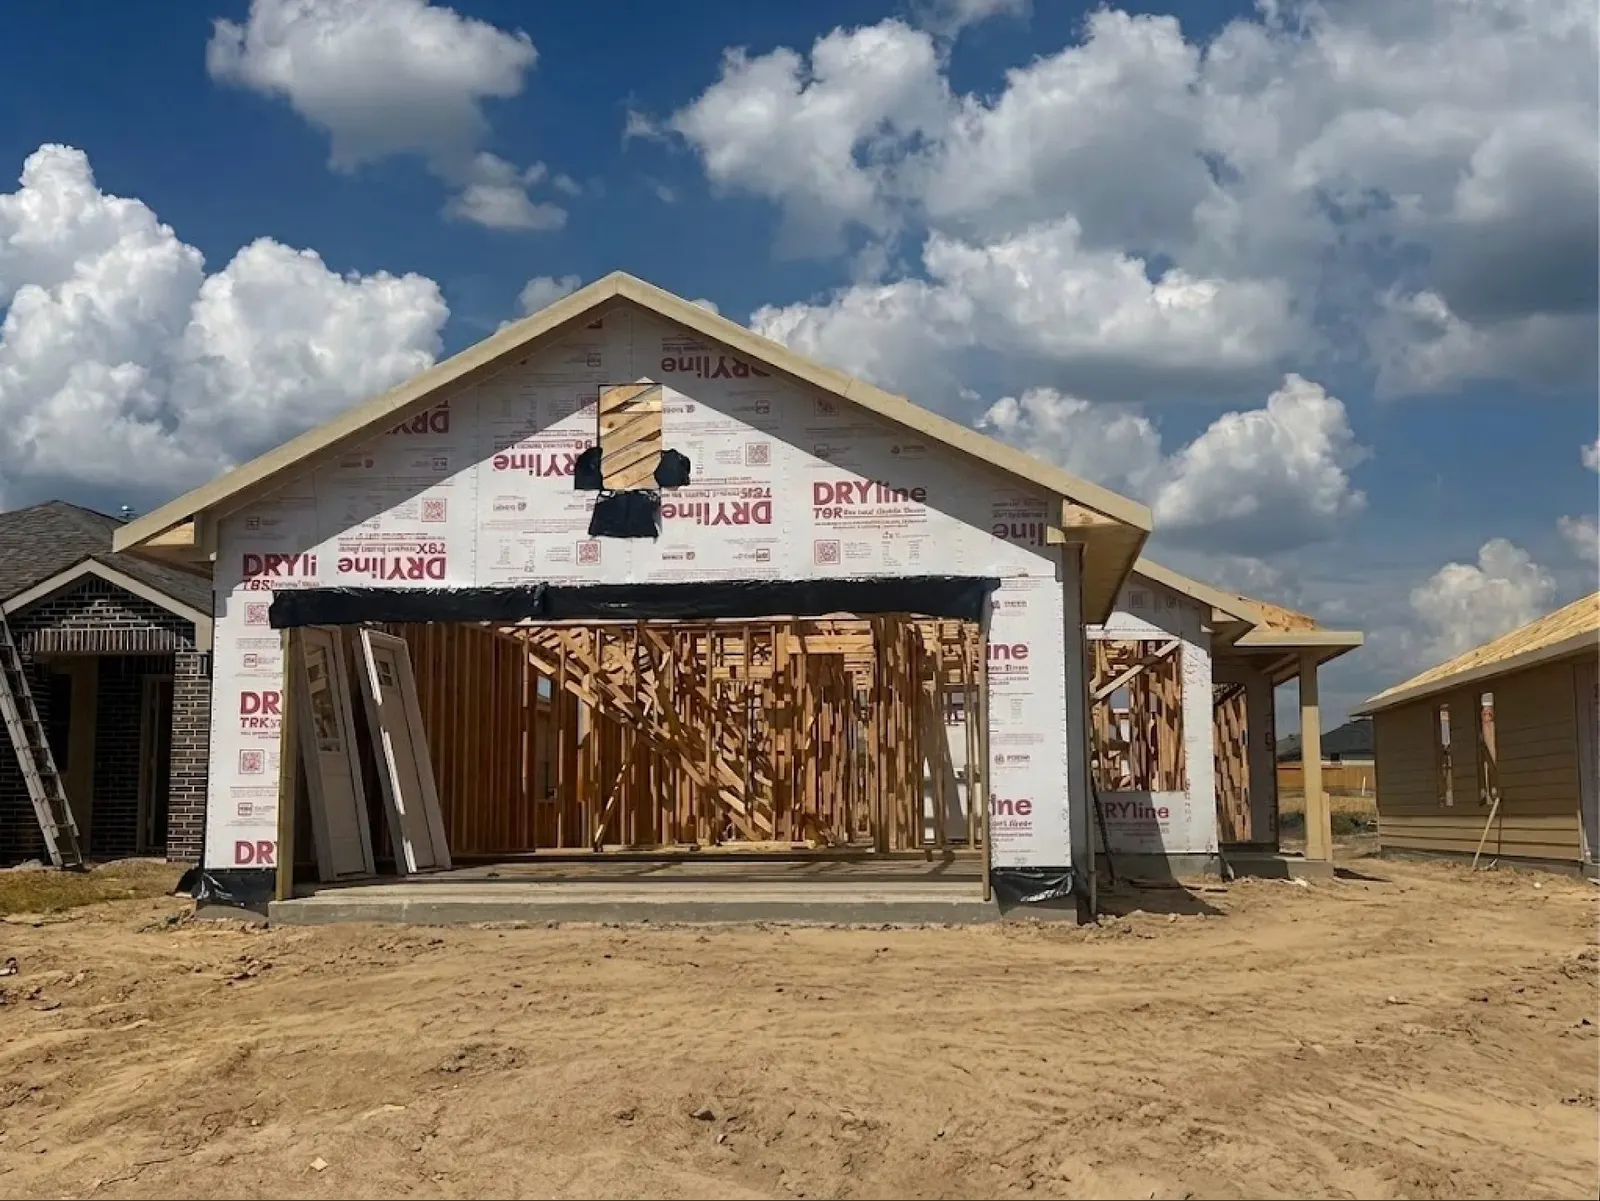
Ask when the home is expected to be ready and what the contract says about schedule changes. Discuss inspections, walkthroughs, deposits, and any financing conditions before committing.
Review warranty coverage and service information and ask which maintenance documents you will receive. A new home can still need upkeep and service, so it helps to understand the process in advance.
Use the available-home listings for a current shortlist. Bring the homes you want to compare and your unanswered questions to a Home Advisor so the visit focuses on your needs.